Financial News Highlights
- Headline and core CPI remained hot in October, exceeding market expectations and leading markets to price in higher interest rates from the Federal Reserve.
- Small business confidence remained stable, but the share of businesses planning to raise prices and wages surged.
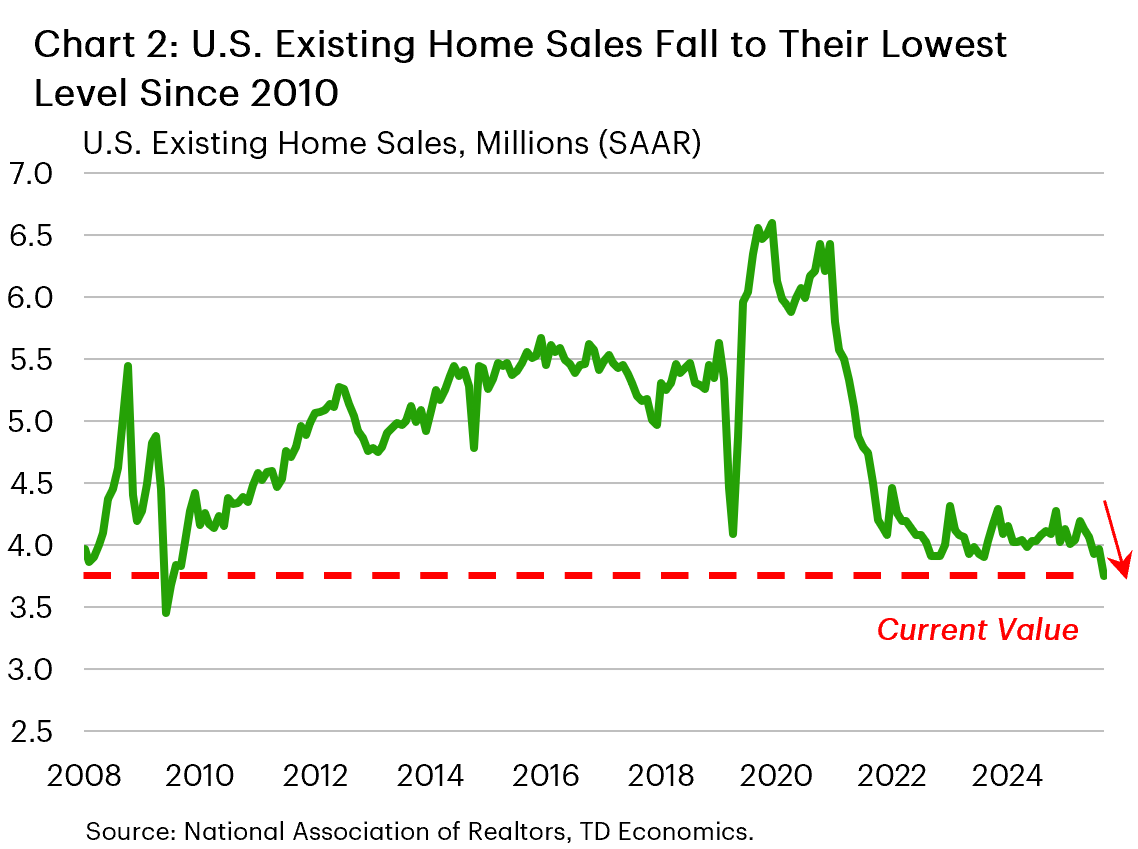
- Existing-home sales fell to their lowest level since August 2010, weighed down by elevated mortgage rates.
Firm Inflation Cements the Case for Another Hike
Financial markets were jolted by another firm inflation report this week. The U.S. dollar and Treasury yields climbed as investors priced in more Fed rate hikes. The 10-year Treasury yield rose from around 4.9% earlier in the week to above 5.1%, reflecting the inflation surprise and hawkish comments from Fed officials. While tech-sector developments also added to the volatility, the swing in the interest rate outlook defined the week’s economic news.
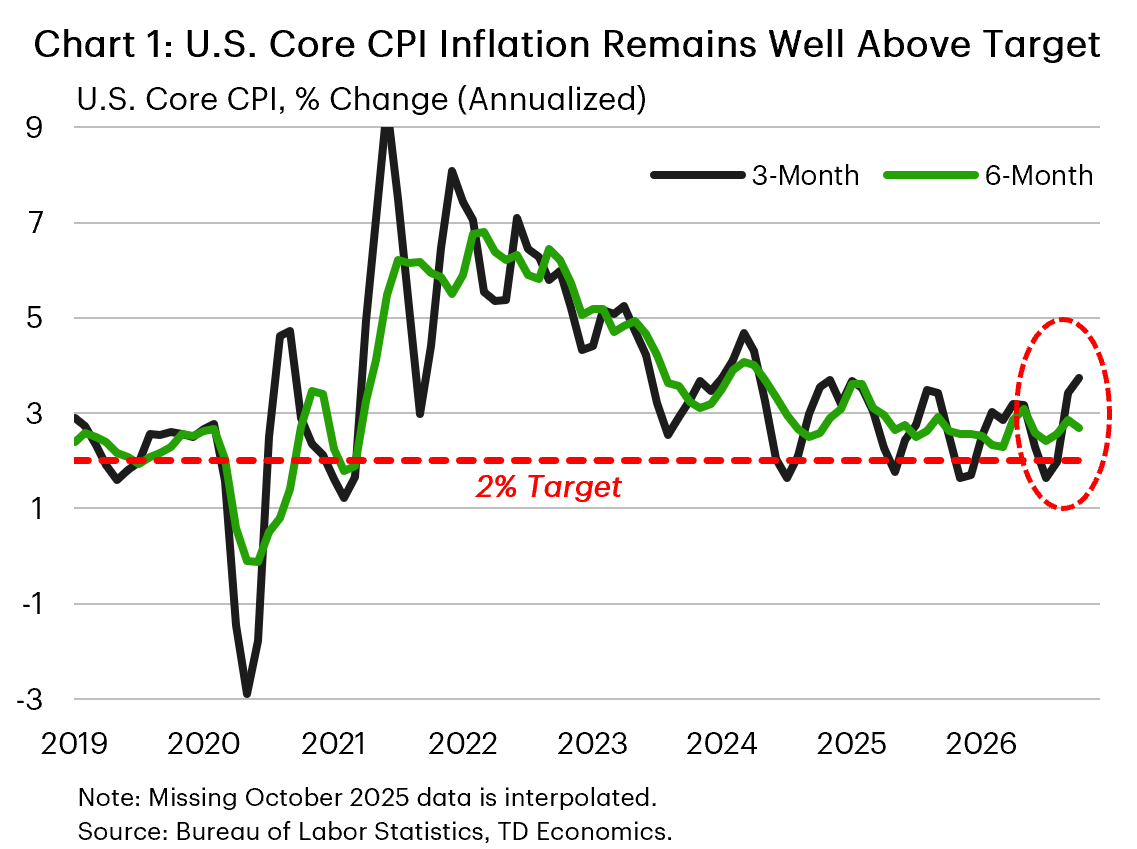
Both headline and core consumer price gains exceeded consensus expectations in October (see here). Missing October 2025 data prevented official year-on-year comparisons, but shorter-term trends confirm that inflation remains too hot for comfort (Chart 1). While the source of inflation pressure has shifted from tariffs to higher energy costs and strong demand for tech-related goods, inflationary pressures appeared fairly broad-based across categories in the October report, and showed little sign of cooling. This broad-based pressure has cemented the case for a December hike.
Fed officials echoed that message with hawkish comments this week. Governor Christopher Waller backed a December rate increase, warning that a larger move could be considered if inflation worsened. Dallas Fed President Lorie Logan argued that at least two more quarter-point increases may be needed, while Philadelphia Fed President Anna Paulson said “further gradual tightening seems appropriate.” Markets are now pricing in a 10% chance that the Fed raises rates half a point in December. Expectations for rates further out shifted higher too. Following the CPI report, markets expect more rate hikes in 2027 than they expected last week, pricing in more than two quarter-point hikes next year on top of December’s move, signalling that markets increasingly expect rates to stay elevated for longer.
The NFIB survey offered further evidence of sticky price pressures, with the net share of small businesses planning to raise selling prices surging 6 points to 37%. Labor market indicators remained healthy, with unfilled job openings rising 4 points to 36% and hiring plans strengthening slightly. This combination of labor market resilience and persistent price pressures gives the Fed room to remain focused on inflation.
This week also delivered fresh evidence that higher rates continue to bite interest-sensitive sectors. Existing-home sales fell 5.5% in October to 3.75 million annualized units, the lowest since August 2010 (Chart 2). Home price growth also slowed to a crawl at 0.4% year-on-year. As highlighted in our recent housing outlook, if mortgage rates remain elevated, the housing recovery will be pushed out further.
Overall, this week’s data cemented the case for another rate increase in December. But the hotter-than expected inflation report, hawkish comments from Fed officials and ongoing economic resilience have increased the odds that rates could rise a bit further and remain elevated for longer.
Admir Kolaj, Economist | 416-944-6318
This Financial News report is provided by TD Economics. It is for informational and educational purposes only as of the date of writing and may not be appropriate for other purposes. The views and opinions expressed may change at any time based on market or other conditions and may not come to pass. This material is not intended to be relied upon as investment advice or recommendations, does not constitute a solicitation to buy or sell securities and should not be considered specific legal, investment or tax advice. The report does not provide material information about the business and affairs of TD Bank Group and the members of TD Economics are not spokespersons for TD Bank Group with respect to its business and affairs. The information contained in this financial news report has been drawn from sources believed to be reliable but is not guaranteed to be accurate or complete. This report contains economic analysis and views, including about future economic and financial markets performance. These are based on certain assumptions and other factors and are subject to inherent risks and uncertainties. The actual outcome may be materially different. The Toronto-Dominion Bank and its affiliates and related entities that comprise the TD Bank Group are not liable for any errors or omissions in the information, analysis or views contained in this report, or for any loss or damage suffered. Do you have any questions about your finances? As financial advisors in Cornelius NC, Naples FL, and Moultonborough NH we are happy to help.
To see more news reports, click here.