Financial News Highlights
- The global bond selloff intensified this week, with the 10-year Treasury yield reaching a new 19-year high.
- A proposed 90-day diesel export ban could lower domestic prices, but also curb refinery output and raise gasoline and global fuel costs.
- This week’s Fed speeches were notably unified, with all officials striking a hawkish tone amid signs that domestic activity is strengthening.
Resilient Growth Keeps the Fed on Edge
The global bond selloff intensified this week, with the U.S. 10-year Treasury yield reaching a 19-year high of 5.22%. The rout reflected a confluence of factors: strong PMI data pointing to resilient growth and persistent inflation pressures, hawkish Fed commentary, and lackluster demand at a five-year Treasury auction. Geopolitical developments added to the uncertainty. Iran’s president told the UN General Assembly that reopening the Strait of Hormuz remained conditional on the U.S. lifting its blockade on Iranian exports, dashing hopes for any near-term diplomatic breakthrough. Even so, oil prices fell 6% on the week to $94 per barrel as Saudi Arabia resumed operations on its East-West Pipeline – a key artery that transports roughly 4% of global oil supply. Meanwhile, the only meaningful outcome from this week’s meeting between President Trump and President Xi was an extension to the U.S.–China trade truce to January 2027, pushing back a November expiry and averting a renewed escalation toward the triple-digit tariffs.
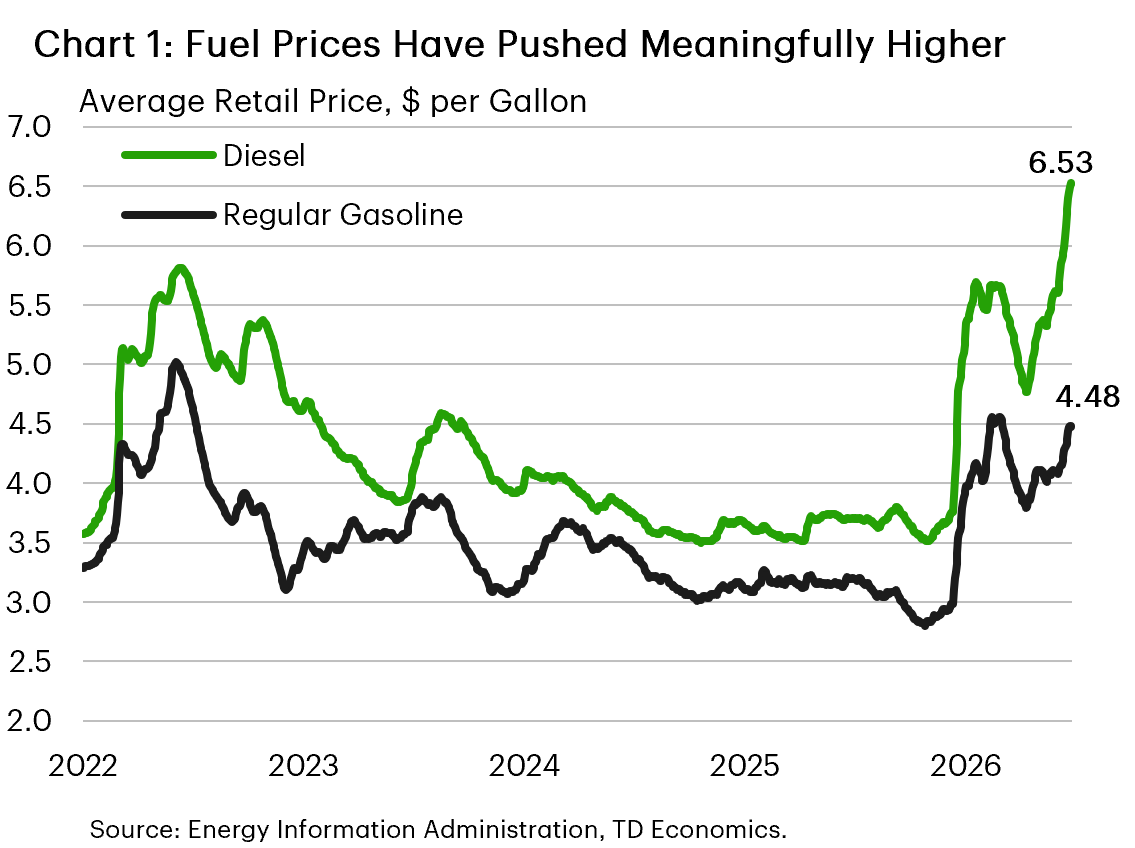
Despite the pullback in crude prices, refined-product markets remain tight. Retail diesel prices climbed above $6.50 per gallon while regular gasoline is hovering at $4.50 (Chart 1). The sharp rise in fuel costs prompted President Trump to propose a 90-day ban on diesel exports. Because the U.S. supplies roughly 20% of globally traded diesel, a ban would immediately redirect more supply to the domestic market, providing some near-term relief at the pump. However, the effects would vary considerably by region. The Gulf Coast, home to more than half of U.S. refining capacity, produces substantially more fuel than it consumes, while the East Coast relies partly on imports. An export ban would therefore strand excess supply on the Gulf Coast while tightening global markets. It could also create broader distortions because refineries jointly produce gasoline, diesel, and jet fuel. If surplus diesel forced refiners to reduce crude throughput, supplies of gasoline and jet fuel could also tighten, adding upward pressure to their prices.
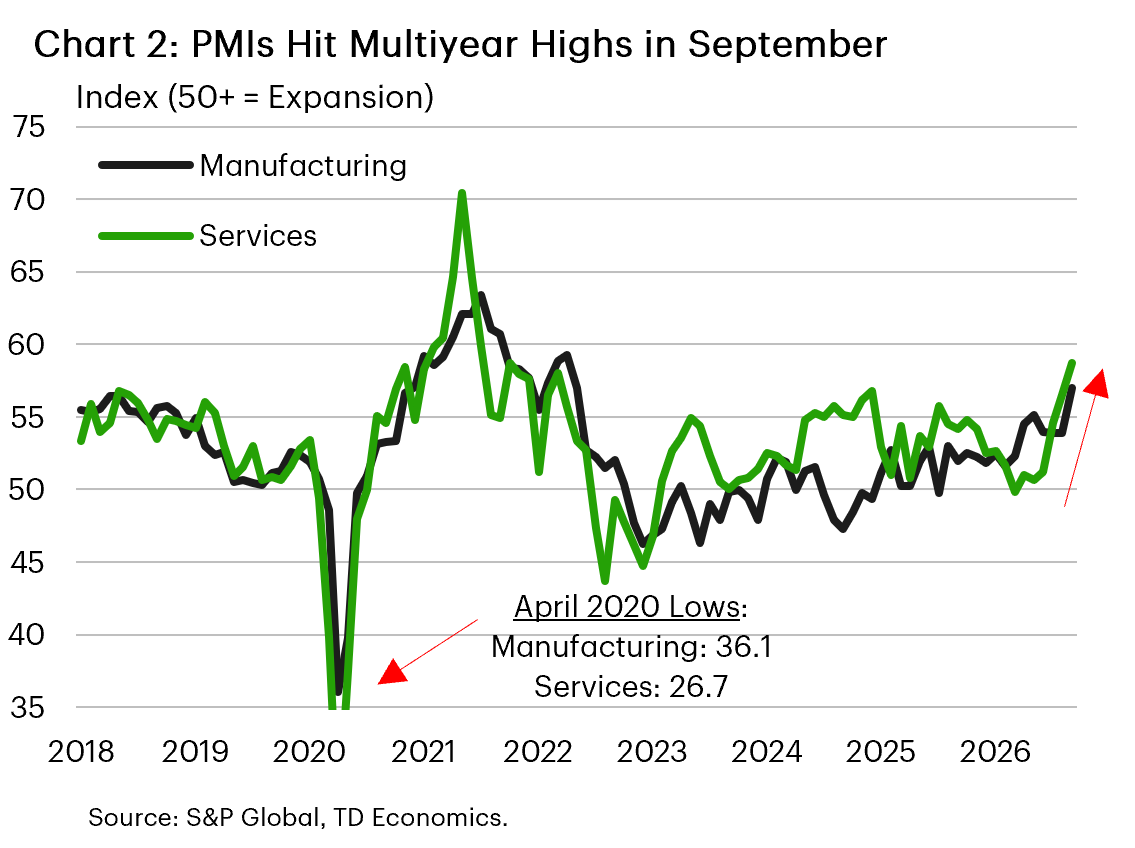
Simply put, there is no easy way to lower refined-product prices without a corresponding pullback in crude oil – and that appears unlikely in the near term. As a result, the second-round effects of higher energy costs may persist longer than previously expected. This has become a growing concern for Fed officials, particularly as strong aggregate demand also appears to be keeping inflation elevated. That concern was reinforced by S&P’s flash estimates of manufacturing and services PMIs for September, which showed activity expanding at its fastest pace in several years (Chart 2). The acceleration was driven largely by sharp gains in new orders and employment, while input costs also rose.
Fed officials had appeared increasingly divided earlier in the year, but this week’s remarks conveyed far greater unity, consistent with last week’s unanimous decision to raise rates. All nine officials who discussed the outlook struck a hawkish tone, and none expressed clear support for a pause. Next week’s August PCE inflation data and September employment report will be key in shaping the Fed’s next decision. Fed futures are currently pricing 66% odds of another hike in October.
Thomas Feltmate, Director & Senior Economist | 416-944-5730
This Financial News report is provided by TD Economics. It is for informational and educational purposes only as of the date of writing and may not be appropriate for other purposes. The views and opinions expressed may change at any time based on market or other conditions and may not come to pass. This material is not intended to be relied upon as investment advice or recommendations, does not constitute a solicitation to buy or sell securities and should not be considered specific legal, investment or tax advice. The report does not provide material information about the business and affairs of TD Bank Group and the members of TD Economics are not spokespersons for TD Bank Group with respect to its business and affairs. The information contained in this financial news report has been drawn from sources believed to be reliable but is not guaranteed to be accurate or complete. This report contains economic analysis and views, including about future economic and financial markets performance. These are based on certain assumptions and other factors and are subject to inherent risks and uncertainties. The actual outcome may be materially different. The Toronto-Dominion Bank and its affiliates and related entities that comprise the TD Bank Group are not liable for any errors or omissions in the information, analysis or views contained in this report, or for any loss or damage suffered. Do you have any questions about your finances? As financial advisors in Cornelius NC, Naples FL, and Moultonborough NH we are happy to help.
To see more news reports, click here.